IMF chief urges US and wealthy nations to rein in debt to ease global economic pressure
 14 October 2026
The U.S. and other wealthy nations need to urgently tackle mounting global debt levels that are weighing most heavily on low-income countries and straining the global financial system, the head of the International Monetary Fund said Wednesday.
IMF Managing Director Kristalina Georgieva said Treasury Secretary Scott Bessent and other U.S. leaders recognize that the federal deficit and national debt are too high. But economic growth alone would not be enough to address the country’s more than $40 trillion in national debt, she said.
Meanwhile, rising bond yields, reflecting higher premiums demanded by investors for taking on greater risk, have been disrupting financial markets.
“We believe that growth, of course, helps, but it cannot deliver fast enough the necessary adjustments,” Georgieva said at the autumn meeting of the IMF and World Bank in Bangkok.
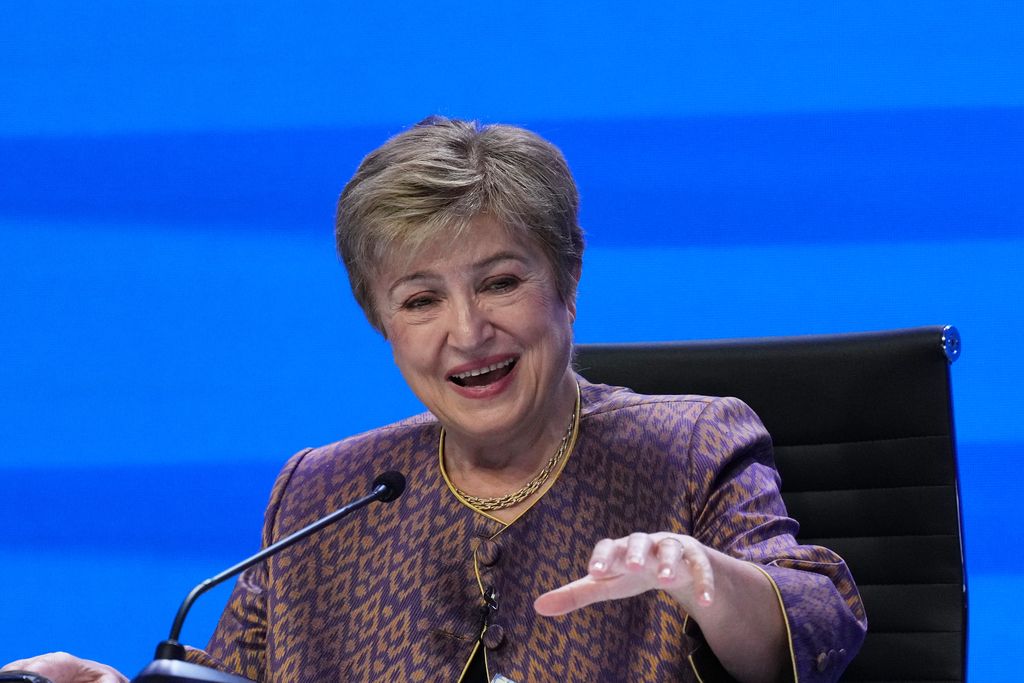
At a news conference, IMF Managing Director Kristalina Georgieva says just trying to grow the U.S. economy out of its more than $40 trillion in national debt would not suffice.
“There is no magic,” she said, adding that other measures would be needed. “You have to go in a direction of tightening, bringing it down, bringing the deficit down.”
‘Fiscal consolidation’ faces challenges
Rising debt levels and global inflation, partly resulting from high energy costs due to the Iran war, have pushed interest rates to multidecade highs, adding to the burdens of the world’s poorest nations.
Efforts to bring debt under control with what Georgieva and other experts call “fiscal consolidation” have suffered setbacks from heavy spending during the COVID-19 pandemic and since.
“Fiscal risks are rising, and a proper reaction is largely absent in many countries,” said Rodrigo Valdes, director of the IMF’s Fiscal Affairs Department. “And in major advanced economies, the effect of fiscal indiscipline does not stop at the border. It travels to the rest of the world.”
“Among the world’s poorest countries, interest payments have reached historic highs relative to revenue, and declining amounts of aid are creating gaps that some countries have been unable to finance,” the IMF’s latest Fiscal Monitor said.
That is forcing countries to make hard choices between supporting their most vulnerable people and meeting their debt repayment obligations.
“The Global South is paying the price for rising interest rates in wealthier countries,” U.K. Foreign Secretary Ed Miliband said at an event on the sidelines of the IMF meetings.
“We need a new deal on debt, a deal that supports countries to repay over longer time horizons and, crucially, refinancing with better rates to give developing countries precious fiscal space,” he said.
Nations need help with job creation and investment
The median developing country pays three times as much in interest as developed countries, said Alexander De Croo, former Belgian prime minister and administrator of the United Nations Development Programme (UNDP).
On average, nearly 10% of government spending goes toward debt repayments. High fuel and fertilizer prices, the effects of the El Niño weather phenomenon and rising borrowing costs have left many low-income countries with little room to recover.
“I mean, we don’t see really a light at the end of the tunnel,” De Croo told The Associated Press.
Creating jobs is another top priority, particularly as the growing use of artificial intelligence threatens to make many traditional occupations obsolete. More than 1.2 billion young people are expected to enter the global workforce over the next decade or so, while forecasts suggest only 400 million net new jobs will be created.
The UNDP this week announced its “Jobs for Prosperity” initiative to bring together governments, development banks — such as the World Bank — and private businesses to encourage investment in sectors such as tourism, healthcare and food processing.
The initiative and related efforts will help countries attract investment by strengthening governance and policies and developing pipelines of “investible projects,” De Croo said. “These are things that are feasible. It’s been proven that you can do it in many places of the world,” he added.
Separately, the IMF, Bank of Thailand and World Bank Group announced a “Bangkok Blueprint” on Wednesday to combat cybercrime, financial fraud and online scams.
The announcement came a day after cyberattacks caused refrigeration systems to overheat at hundreds of stores in France. —BANGKOK (AP)
________
Story by ELAINE KURTENBACH | Associated Press
Associated Press journalists Haruka Nuga and Tian Macleod Ji contributed to this report.